
Regulatory volatility and policy friction, by contrast, introduce significant risk premiums, weaken private-sector confidence and limit potential growth.
Over the past fifteen years working in Slovak public affairs, I have watched the country develop into a major center of European automotive manufacturing. However, Slovakia’s traditional economic model has reached its structural limits. The country now faces a volatile macro-fiscal and legislative period as the government begins debating next year’s state budget against the backdrop of the parliamentary elections expected in late 2027. In such a highly polarized environment, the pressure to favor short-term electoral spending over structural reform poses a serious challenge. For international business leaders, this budget cycle will be a direct test of Slovakia’s commitment to long-term predictability.
The Slovak Competitiveness Deficit in Numbers
According to the IMD World Competitiveness Index, Slovakia’s score continued to decline, reaching 42.50 points in 2026 and placing the country 58th out of 70 economies worldwide. This puts Slovakia well behind Austria in 27th place, the Czech Republic in 30th and Poland in 36th.
Several persistent problems lie behind this decline. Recent surveys show that only 35% of companies are confident that the courts protect their investments, while 34% point to unpredictable and non-transparent conduct by public authorities. Confidence in the judiciary is also low, with only 38% of businesses considering the courts independent. In addition, 61% of executives describe corruption as a major obstacle to doing business, and 40% say it has directly prevented them from winning public contracts.
The 2024 public procurement reforms raised the threshold below which contracts do not have to be published to €50,000, prompting concerns among businesses about transparency and fair competition. At the same time, Slovakia fell to 57th place globally in digital competitiveness. It ranked last, in 69th place, for corporate flexibility and adaptability, and 68th for the availability of highly qualified foreign personnel. These rigidities have created a severe talent shortage and are holding back the shift towards higher-value-added activities.
The Macro-Fiscal Tightrope and the Consolidation Trap
This regulatory and institutional stagnation also directly threatens Slovakia’s fiscal sustainability. The general government deficit reached 4.5% of GDP in 2025 and is projected to rise to 4.6% in 2026. Public debt is on an unsustainable path and, without major spending reforms, is expected to increase from 61% of GDP to more than 100% by 2040.
Rather than improving efficiency on the expenditure side, for example by phasing out untargeted natural gas subsidies or means-testing the 13th pension, the government has relied almost exclusively on tax-based consolidation to finance social spending ahead of the upcoming election. The measures include higher corporate tax rates, corporate income tax brackets, an increase in the standard VAT rate to 23% and a new financial transaction tax on payment services. This approach makes the tax system more complex and places a heavy burden on the business environment. It also pushes Slovakia’s effective corporate tax rate above those of Czechia, Poland and Hungary. The resulting cost pressure is compounded by a sharp increase in late payments from private entities. In 2025, 62.4% of firms reported late payments, compared with 51.2% in 2024, putting further strain on corporate liquidity.
The Sovereign Risk of Funding Disruption
For the international business community, the most immediate risk is the possible suspension of European Union funding. Slovakia depends heavily on EU capital inflows, which co-finance up to 80% of all public investment. This funding is essential for large infrastructure projects, the digitalization of public administration and the transition to green manufacturing. It is also important for the electric vehicle sector, where Slovakia’s domestic EV adoption rate remains at just 3%.
However, growing disputes between Slovak authorities and EU institutions have put these resources at risk. In May 2026, the European Parliament adopted a formal resolution by 347 votes to 165. It warned of systemic compliance risks and urged the European Commission to activate the EU budget conditionality mechanism and suspend payments to Slovakia. A formal suspension would severely disrupt the public investment pipeline, increase sovereign borrowing costs and trigger serious macroeconomic instability.
Advocacy Priorities
To protect Slovakia’s investment climate, we must actively advocate for structural predictability. Our collective efforts should focus on three priorities:
- Restoring legislative predictability - We must urge the government to limit its frequent use of fast-track legislative procedures, which bypassed standard stakeholder consultations for 40% of laws in 2025. We should also demand rigorous, evidence-based impact assessments before new tax or regulatory measures are introduced.
- Advocating for expenditure-led fiscal balance - Instead of imposing regressive corporate levies and transaction taxes that weaken cost competitiveness, we must advocate for disciplined spending controls, including means-testing social benefits and removing broad-based energy subsidies.
- Securing the European partnership - We must encourage constructive dialogue between Slovak policymakers and EU institutions to resolve compliance and constitutional disputes and maintain a stable, uninterrupted flow of EU co-financing.
Slovakia’s long-term prosperity cannot rest on electoral short-termism or an increasingly complex tax system. By promoting institutional stability, legislative predictability and fiscal discipline, we can help create a stable investment environment in which international businesses can thrive.
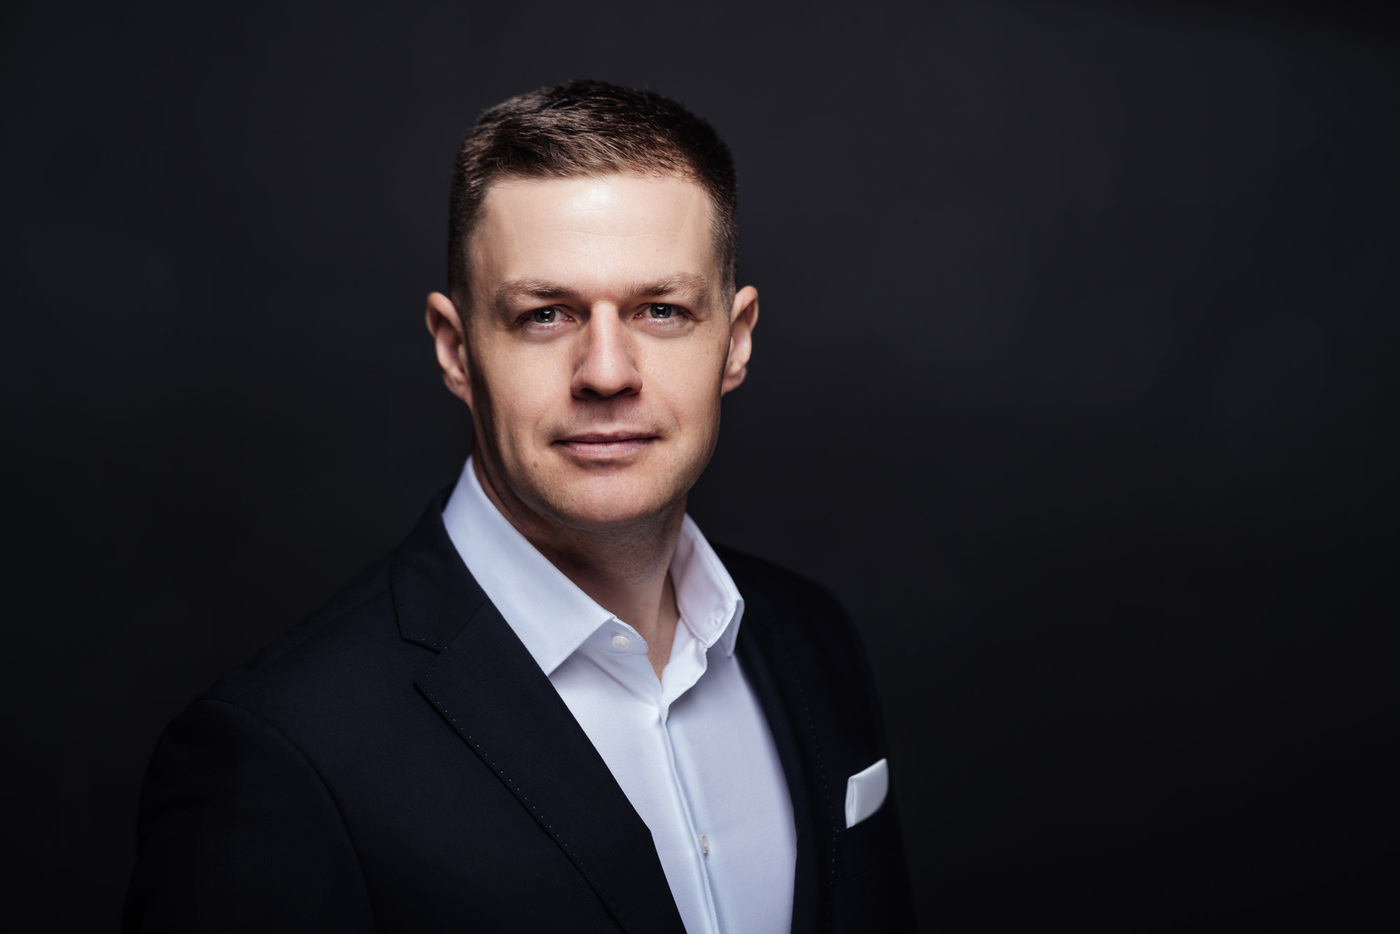
Tomáš Bereta, Partner, FIPRA Slovakia
Follow us